WealthTradie.com
The Master strategy for Fix and Flippers
Maximize Your ROI with the HEIA Liaison License for Flippers
Transform your real estate fix and flipping business with the HEIA Liaison License. Unlock equity-based financing, reduce upfront costs, and ensure higher returns for every property you flip. Join the growing network of innovative flippers revolutionizing the game with Home Equity Invoice Agreements.
30 Day No-Questions Money Back Guarantee
MOST Flippers ARe STRUGGLING WITH capital
Why Fix-and-Flippers Choose the HEIA Liaison License
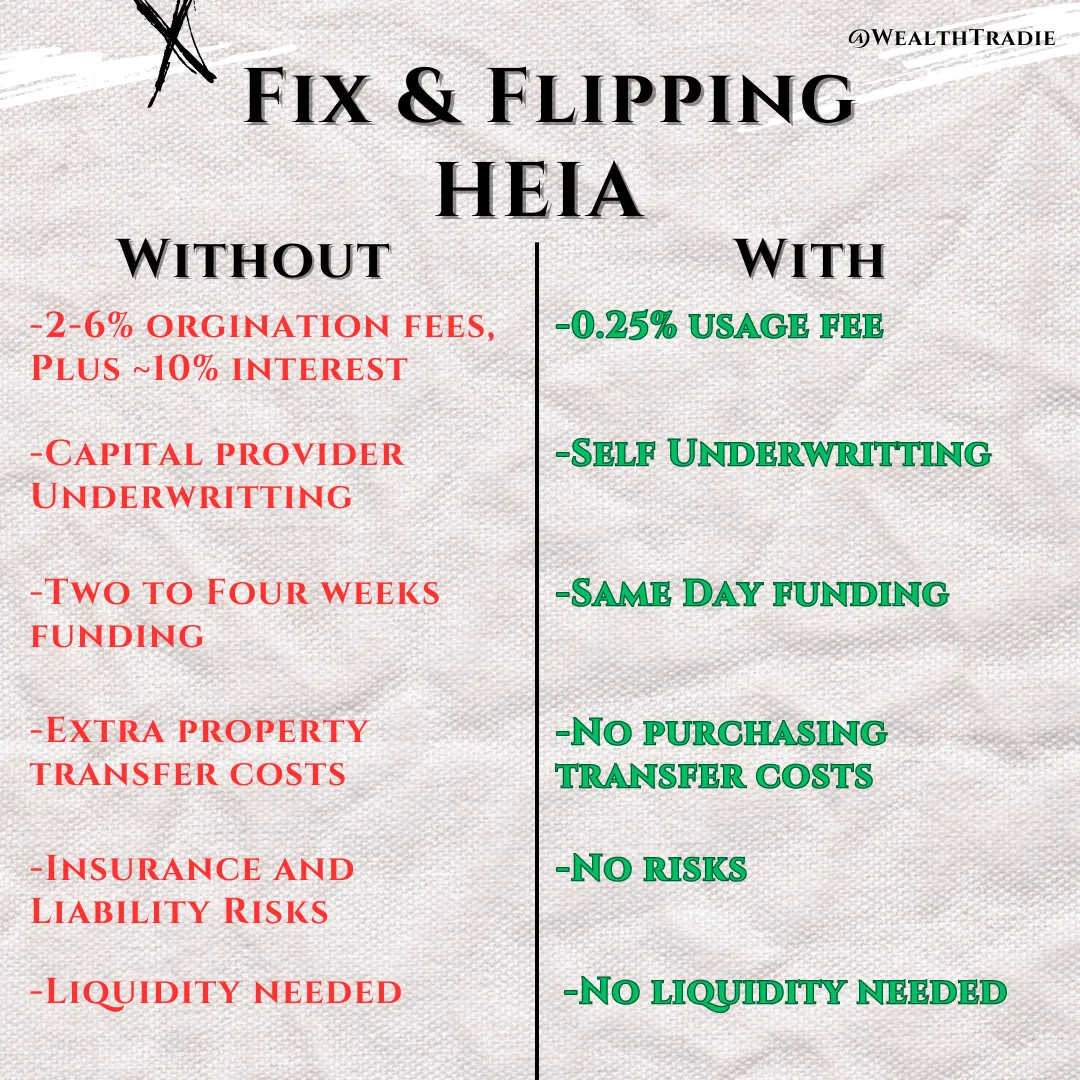
Boost Your Bottom Line
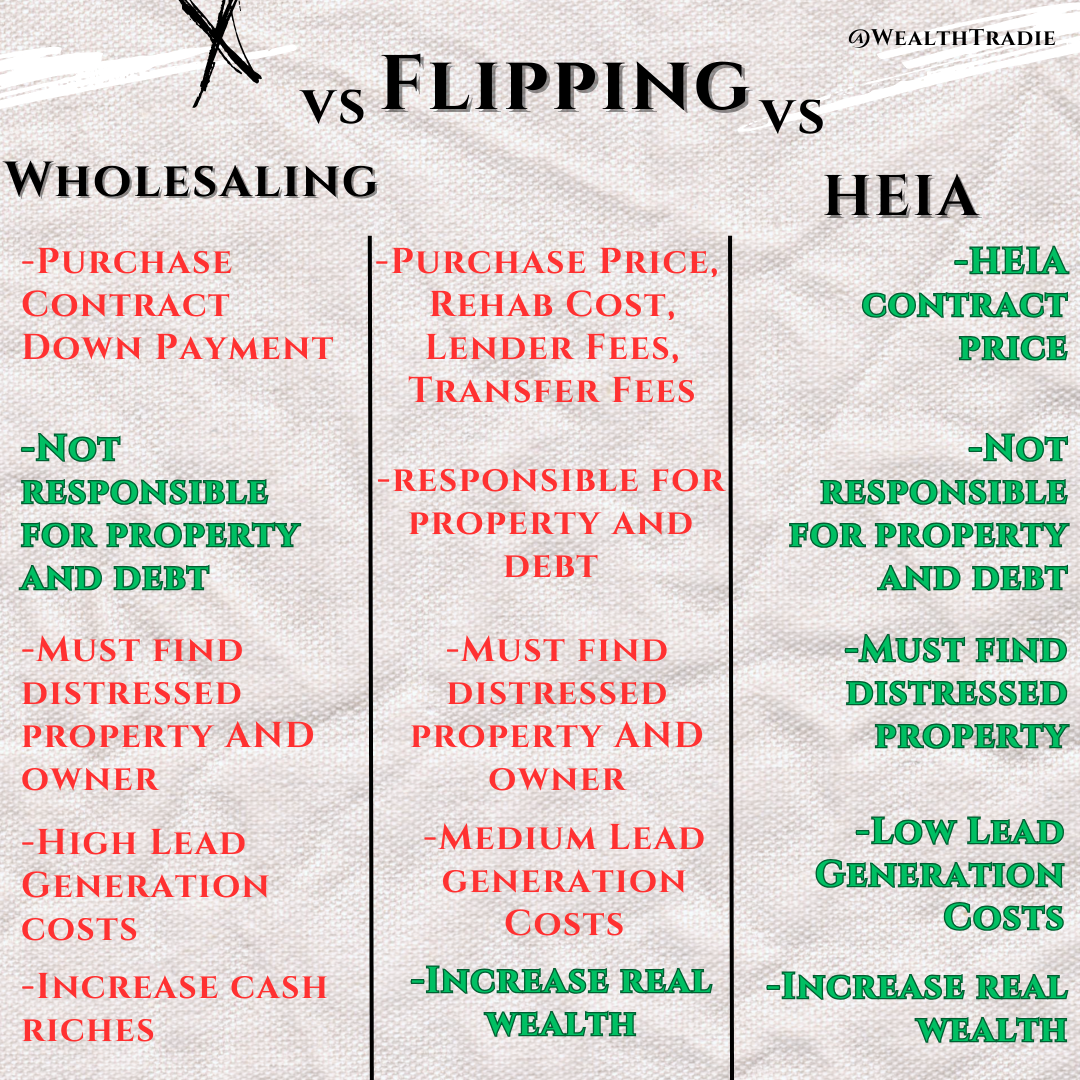
With HEIA (Home Equity Invoice Agreements), you can leverage a property’s equity to purchase property and finance renovations without relying on cash or high-interest loans. Protect your capital and reduce financial exposure while maximizing your profits.
Flip More Properties, Faster
Access equity-based financing for multiple projects simultaneously.
Reduce delays caused by cash flow constraints or traditional hard money financing issues.
Streamline deals and close projects faster with equity backed solutions for homeowners and contractors.
Minimize Your Financial Risk
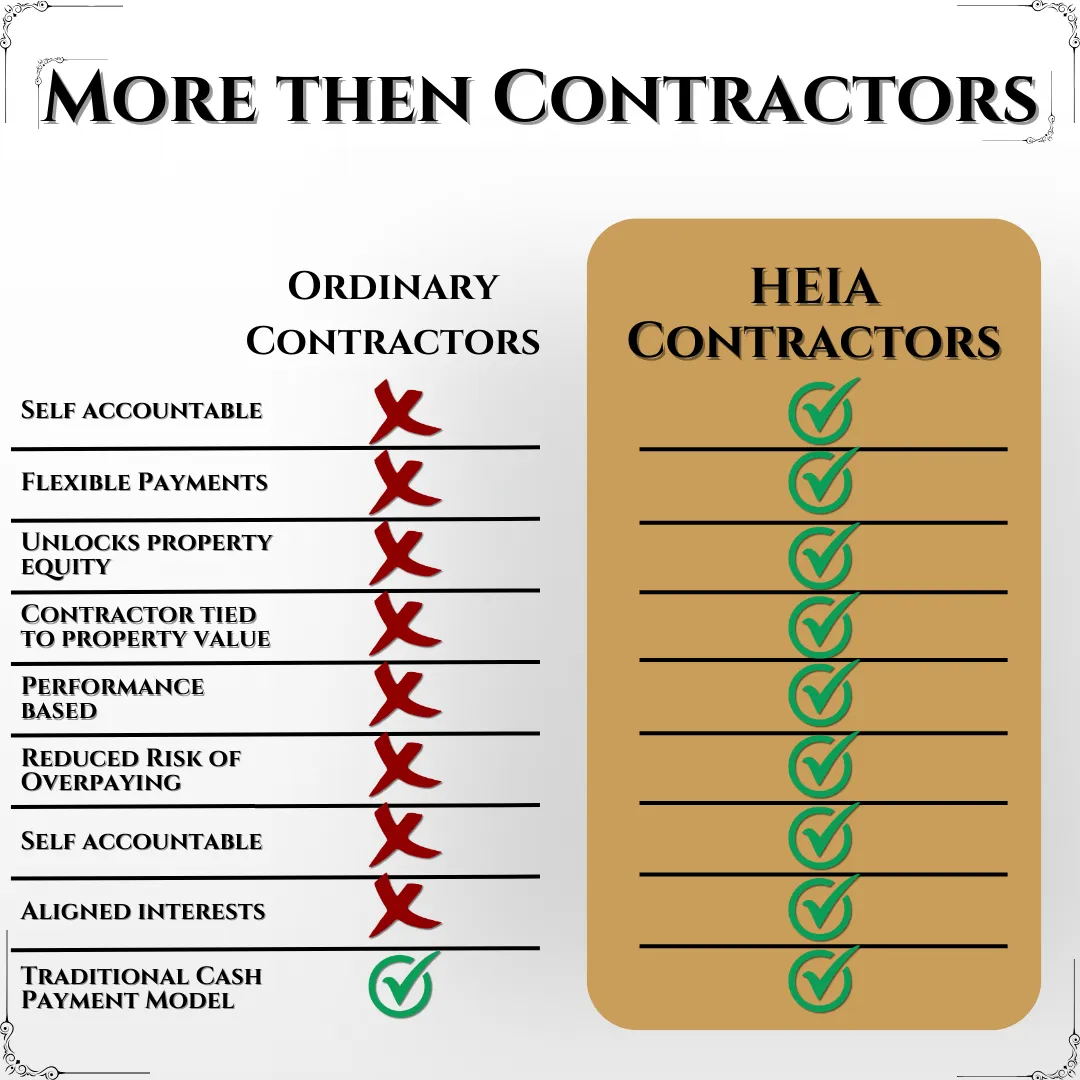
By tying contractor payments to the property’s equity, HEIA aligns everyone’s interests, ensuring high-quality work that maximizes the property’s market value. When the property appreciates, so does your profit.
Step-by-Step List:
How HEIA Works for Fix-and-Flippers
Secure Properties with Potential
Target homes with untapped equity and potential for significant appreciation.
Use HEIA to Fund Renovations
Turn renovation costs into an equity agreement, reducing upfront construction cash needed with no purchasing capital needed.
Sell the Property and Reap the Rewards
When the property sells, both you and the contractor benefit from it's appreciation, ensuring a win-win outcome.
CLICK BELOW TO WATCH FIRST!
Revolutionizing the way fix-and-flippers fund and grow their businesses without the stranglehold of lenders and liquid capital.
INTRODUCING:
Key Benefits of the HEIA Liaison License
Increase ROI on Every Flip
Lower upfront and total costs to improve margins.
Align everyone’s goals with equity-based payouts, leading to better results and higher sale prices.
Ensure High-Quality Work
HEIA ties contractor payments to the home’s final value, ensuring quality and accountability throughout the project. No more chasing contractors or compromising on craftsmanship on a liquid budget.
Scale Your Business with Ease
Take on more projects without the capital stress.
Leverage equity to fund renovations across multiple properties at once with no liquid capital.
Don’t let capital constraints or unreliable contractors slow you down. With a HEIA Liaison License, you’ll scale your flipping business, ensure top-quality renovations, and maximize leverage.
Start building smarter today!
30 Day No-Questions Money Back Guarantee
Stop Letting capital Hold You Back
Transform Your Fix-and-Flip Game with a
HEIA Liaison License
Before / Old Way
Frustration with Funding Delays: Endless paperwork, slow approvals, and missed opportunities because of lender red tape.
Contractor Quality Concerns: Fear of shaddy workmanship or contractors abandoning projects.
Costly Bank Fees and Interest: Paying more to lenders eats into your profits and slows your scaling potential.
Limited Scalability: Dependence on lender timelines and cash flow issues limit the number of projects you can tackle.
Fear of Risk: Worrying about making a bad investment or losing money due to unreliable financing or contractors.
After / New Way
Fast, Flexible Financing: Acquire properties immediately and fund renovations using direct equity, not cash or loans.
Self-Accountable Contractors: tie contractor payouts to property value, ensuring high-quality work.
Lower Costs, Higher Profits: Eliminate traditional lending fees and maximize your profit margin.
Uncapped Growth: Take on more flips simultaneously without waiting on capital or juggling liquidity issues.
Confidence and Control: With HEIA, you have a clear, performance-driven structure to ensure success and scalability.
30 Day No-Questions Money Back Guarantee
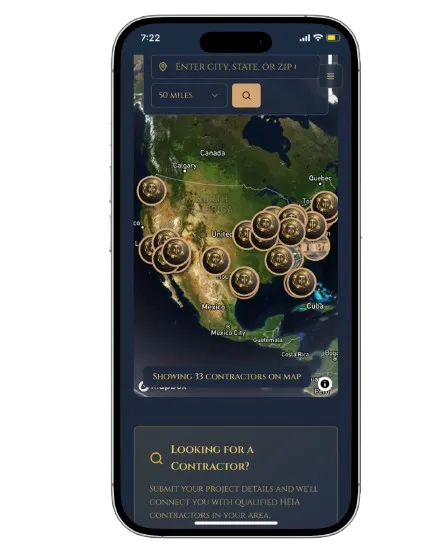
Connect with a contractor today!
We wouldn't be at the tip of the spear leading this movement without understanding how hard it is to teach an old dog (investors) new tricks. don't believe our shiny red dress, connect with the boots on the ground and see for yourself with your current properties. WE guarantee that you will be able to see the difference and want your license on your next project.
Introducing:
WealthTradie Master:
HEIA Liaison License
The #1 Scaling Method for Real Estate Investors
Here's Everything you get:
Step-by-Step Training Value: $5,611
A structured video series that walks you through each phase, ensuring you have everything you need to achieve using HEIA efficiently.
Personalized Implementation Plan Value: $250
A customized roadmap tailored to your specific goals, ensuring you take the right steps toward success with your real estate strategies.
Exclusive Q&A Sessions Value: $recurring
Get direct access to WealthTradie experts for ongoing support and clarity, helping you overcome challenges quickly.
Lifetime Wealth Multiplier Calculator Value: $270
Receive all future updates to the program, ensuring you stay ahead with the latest tools.
Done-for-You Contracts Value: $3,714
Save time and effort with ready-to-use documents that are designed for immediate implementation.
Normally: $an entire college degree
Today: A fraction of the costs
30 Day No-Questions Money Back Guarantee
PLUS, YOU ALSO GET
Amazing Bonuses When You Join Today
Bonus 1: WealthTradie Apprenticeship
Unparalleled Tools for Scaling Like a Pro
With WealthTradie’s Apprentice Membership, you gain exclusive access to premium resources: advanced calculators, property valuation tools, and comprehensive market analysis guides. Plus, enjoy priority support and insider updates on the latest trends and opportunities in real estate.
Bonus 2: Pro Membership
Master the Game of Real Estate Wealth
Gain insider knowledge and hands-on training from seasoned experts with the WealthTradie Apprenticeship. This program takes you step by step through proven strategies to scale your fix-and-flip business, master HEIAs, and create sustainable wealth. Learn everything from deal sourcing and negotiation to maximizing profits with equity-based agreements.
Bonus 3: Full 100% Revenue Share Affiliate Membership
Earn While You Scale
Unlock the ultimate side income opportunity with WealthTradie’s Affiliate Membership. With 100% revenue share, you’ll keep all the profits from referring other fix-and-flippers or real estate professionals to HEIA and WealthTradie memberships. Turn your network into a profit machine while helping others break free from traditional lending.
30 Day No-Questions Money Back Guarantee
Revolutionary
How others are utilizing HEIAs
Foreclosure Defense: Exposing Mortgage Fraud
Foreclosure Defense, Mortgage Fraud, Homeowner Empowerment
The Deed of Repentance: A “Little Short” for Homeowners Trapped in Mortgage Fraud
This article explains, in plain language, a structured five‑month Deed of Repentance process that homeowners can use to expose fraud, demand clarity, and reclaim a measure of power in the face of modern mortgage and foreclosure practices.
Why This Is Called the “Little Short”
Anyone who has seen The Big Short understands that film is more than entertainment — it is essentially a confession. It illustrates how deeply corrupt and unaccountable the mortgage world became, and how almost nobody was truly keeping track of the financial instruments being created and traded on people’s homes, neighborhoods, and lives. The central characters were not simply “lucky”; they created a new instrument, saw through the game, and then everyone else scrambled to copy them.
The Deed of Repentance can be understood in a similar way: as a shorting (clarifying) instrument — but not for Wall Street. It is for the homeowner. Instead of a “Big Short,” this process functions as a Little Short. It is not about betting against the housing market; it is about calling out fraud, confusion, and dishonor buried inside mortgage paperwork and demanding clarity on the actual title to real property. This is where homeowner empowerment lives — in the details that were never clearly explained, largely because it has never been in the industry’s interest to do so.
Public vs. Private: The Two Worlds Your Mortgage Lives In
A core idea behind the Deed of Repentance is that there is a public side and a private side to almost everything related to a mortgage and property. This is not just a legal technicality — it represents two different worlds interacting every time something is signed, recorded, or taken into court. There is the promissory note, the deed of trust or mortgage, the security assignment, the title, the abstract, the recorded documents — and then there is what actually happened between living, breathing human beings when a “loan” was obtained for a home.
Many people assume, “We have regulators. We have the SEC. We have enforcement. We’ve seen The Wolf of Wall Street; surely someone is cracking down.” Returning to The Big Short reveals a different reality: there are massive incentives to keep this system alive, even when it is built on fraud and confusion. In practice, almost nobody steps in to uphold real standards on behalf of the homeowner.
In this environment, the burden effectively lands on the homeowner. The homeowner is the one holding the liability, the one who is not allowed to be “ignorant of the law,” even while the system allows judicial officers to operate with what has been called “reasonable ignorance” — a posture that Heinz vs North Carolina helped normalize for themselves. Courts and officials may be permitted to be ignorant; homeowners are not. That imbalance is worth serious reflection!
Real power starts with organized records, proper notices, and documented standards.
What the Deed of Repentance Actually Is
The Deed of Repentance (DoR) is a structured, five‑month private administrative process. It is not a magic letter or a one‑page template downloaded from the internet. Instead, it is a series of correspondences sent with precision and accountability, using tools that have always existed: neighbors as witnesses, a notary, and the United States Postal Service (USPS).
The approach draws inspiration from the work of Cal Washington and the InPowerMovement, particularly their use of Notices of Liability. That general framework is adapted here specifically to mortgages and real property. In essence, the Deed of Repentance is a notification and contract structure in which the homeowner, as the true owner and “lord of the land,” communicates: “If there is fraud or confusion in this mortgage, I require clarity. If you remain silent, that silence will have consequences(peaceful private remedy).”
💡 Homeowner Mindset Shift: In practice, no one in the system carries the ultimate liability for a home except the homeowner — not the realtor, not the title company, not the bank’s attorney, not even a judge(mediator) or sheriff. Once that reality is understood, homeowners can stop waiting to be rescued and begin acting as the actual owners, the lords of the land.
The 5-Step Deed of Repentance Process for Homeowners
The Deed of Repentance can be understood as a five‑step, five‑month private remedy that runs alongside — and often underneath — whatever is happening publicly with a mortgage or foreclosure. The basic practical requirements are simple: two witnesses, a notary, and USPS. The goal is to build a documented trail of honor and accountability while offering a private and openable remedy to the liabilities discovered along the way, instead of public ones that may end up in an non erasable record along with liberty/criminal charges NOT open to discussion(contract).
Step 1: The Deed of Repentance Letter (Day 0–14)
The first step is the core Deed of Repentance letter. This is a notification and repentance document that begins with an uncommon but powerful move: the homeowner acknowledges their own prior confusion. The letter recognizes that, at the time of signing the original mortgage, the homeowner may not have fully understood the instruments involved — the separation between the promissory note and the deed of trust, the security assignments, or how the currency systems actually operate.
In this document, the homeowner asks for forgiveness and clarity, but does so inside a contract structure with built‑in accountability. The letter makes specific requests, such as: production of the original wet‑ink notes, a full accounting, and clear evidence of who actually holds the liability and the right to enforce. It references relevant laws and the legal distinction between the note and the security instrument, aiming to establish a genuine meeting of the minds, which is required for any valid contract.
This Deed of Repentance letter is then sent via USPS certified mail, with witnesses and notary involvement where appropriate, and the recipient is given 14 days to respond in honor.
Step 2: Notice to Respond to the DOR (Day 14–28)
If, after those first 14 days, there is no response or an improper response — for example, a reply that dodges the questions, refuses to supply the requested documents, or ignores the accountability structure (being contempt)— the process moves to Step 2: a formal Notice of Sin tied back to the original Deed of Repentance.
This notice essentially states: “You have been given a fair opportunity to clarify this liability. Your silence or dishonor is now being formally noted. The private administrative remedy outlined in the Deed of Repentance is moving forward.” The notice focuses on full accountability, making it clear that the parties involved will not quietly escape their obligations.
Again, the notice is grounded in law and contract. It may remind the recipient that, although Heinz vs North Carolina allows judicial officers a degree of “reasonable ignorance,” the homeowner does not have that luxury and now neither do they. The law is placed squarely in front of all parties so everyone understands what is at stake. A new 14‑day clock begins as soon as this notice enters the recipient’s world, to allow further honorable due diligence to the respondants.
Step 3: Reproof of Sin (Around Day 30)
After roughly 30 days from the original Deed of Repentance, if silence or dishonor continues, the next step is a document often called the Reproof of Sin. The phrase is strong, but accurate: it formally records that, for approximately 30 days, the homeowner has honorably and peacefully attempted to obtain clarity on the liability tied to the property, and that the other party has chosen not to respond, or has responded in dishonor and now agrees through silent tacit agreement to the peaceful private remedy openly discussed over a bonafide meeting of minds, due to the help of witness's and USPS.
The Reproof of Sin restates the entire timeline, the documents sent, the specific failures to respond, and the obligations/judgements that are being avoided. It reinforces the mechanics that liability is a form of currency. When a party refuses to clarify who holds which liability, they are effectively playing games with the very currency they claim to manage, yet now they are bound into one that they know you now are aware to the true standards to.
Step 4: The Real True Bill – Your Private Invoice (Day 30–90)
At the same time the Reproof of Sin is sent, the homeowner issues what is called the Real True Bill. This is a private bill of exchange — an invoice/debt/lien that reflects the fraud, iniquities, confusion, and dishonor documented throughout the Deed of Repentance process. It is not merely a complaint; it is a monetized claim, a private and peaceful remedy for the harm caused by the other party’s actions and omissions.
In the public financial world, a bill that goes unpaid for 90 days generally goes into default. The Real True Bill applies the same principle in the private realm. After 90 days without a proper response or settlement, that private bill of exchange becomes bona fide — a collectible claim against the respondent and by any holder of the bill (just like "cash" or a blank money order). If the bill is paid, responded to, or settled, that outcome is effectively cash. If it is ignored, the default itself becomes part of the homeowner’s remedy too. They now get to use/circulate the new currency they LITERALLY printed (just how all other paper United State Dollar, USD, currencies are).
Either way, as long as the homeowner maintains clean books and full accountability, they begin to operate more like a bank: creating and managing private currency tied to the underlying liability. Some might even say they are also starting to operate like or even better then a public court does/can.
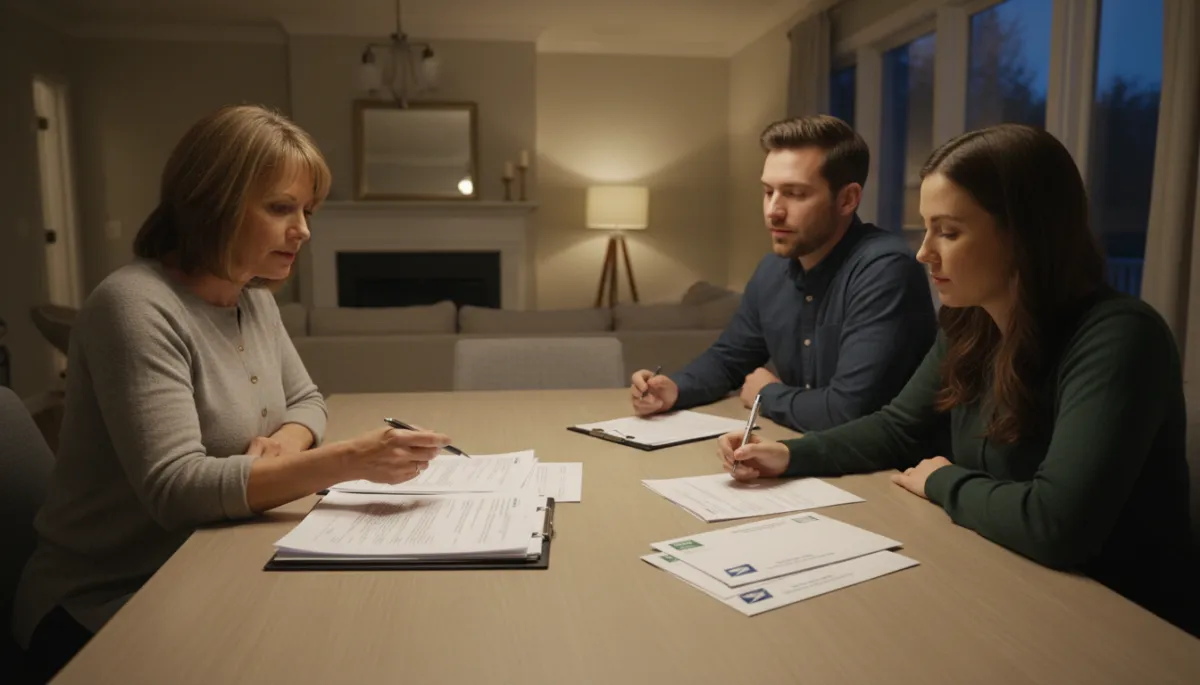
Witnesses, notaries, and USPS turn your private process into enforceable evidence(debts).
Step 5: From Private Remedy to Public Enforcement (After Day 90)
Once the Real True Bill has remained in default for 90 days, the homeowner holds a completed private administrative record/lien against the respondents. The Reproof of Sin, the Deed of Repentance, the formal Notice of Sin, the timelines, USPS proofs of mailing, the witness's, and notarial evidence together form what can be viewed as an “anti‑mortgage bond certificate” — a counter‑instrument to the questionable mortgage structure originally attached to the property.
At this stage, the homeowner has options. The instrument can be moved publicly or privately, and that choice matters. Once something is fully taken into the public, it can be difficult to pull it back into the private. However, by understanding the notarial process of dishonor — the public system’s version of a debts final notice of default — a homeowner can hand the private record summary to the public side in a way that compels public enforcement based on the privately structured record. This is where the worlds of public and private finally intersect in the homeowner’s favor, instead of simply steamrolling them.
💡 Homeowner Caution: It is also important to recognize that when a homeowner starts operating in honor and demanding clarity, there may be “gnashing of teeth” in local public systems and among their water‑cooler circles — resistance, gossip, and pushback — until enough learning and correction occurs for those systems to return to truth and understanding. That turbulence does not necessarily mean the homeowner is wrong; it often signals that a long‑standing passive role is finally being abandoned.
Why This Matters for Almost Every Homeowner
Many researchers and practitioners conclude, based on years of observation, that 90–99% of modern mortgages are fraudulently structured. The separation of the note and the security instrument, securitization practices, lack of full disclosure, and the way the industries systems obscures who created what value — all of it tends to keep homeowners in the dark while extracting maximum value from their property and labor. The 2008 crisis exposed just how much “uncreditworthiness” and dishonor was baked into the banking system, only to be pushed onto homeowners as if the failures were theirs instead of the true master of the bargain creators.
The Deed of Repentance represents a structured way of saying: “No more.” It does not assume the system will suddenly become honest, nor does it suggest that hiring an attorney or title executive will automatically resolve these issues. Those industries are often structured to protect themselves first, regardless of how much a homeowner pays or how many percentage points of a sale are surrendered.
In reality, the homeowner is the only party truly on the hook. Given that reality, it makes sense for homeowners to learn how to operate as the lord of the land, rather than as confused tenants in their own houses. When they start to empower themselves, they start waking up to being the honorable shepherd of the liabilities that his flock can not deny any longer.
Think Like George Washington, Not a Passive Borrower
A closer study of George Washington, beyond the myths, shows that it was not simply “guns blazing” that secured freedom outcomes. It was correspondence — the timing, content, and precision of letters, orders, and agreements. The Deed of Repentance functions in a similar way. It is about the “spells” written down: carefully chosen words placed on paper, witnessed, notarized, and sent through USPS (Benjamin Franklin as Postmaster), which bind other parties to action in ways that most homeowners have never considered doing themselves.
This is not about storming a bank with pitchforks. It is about calmly documenting dishonor, building a private record(currency), and then presenting that record to the public side in a way that is difficult to ignore. It is about standing ground in honor and making sense of a system the homeowner did not knowingly create or allow, but refuses to be crushed by. That is what homeowner empowerment looks like in practice — not slogans or hallmarks, but structured action over time.
Disclaimer and Practical Next Steps
It is essential to be absolutely clear: none of this is law or legal(there IS a difference) advice. This material does not create an attorney‑client relationship and does not instruct anyone on what they should or should not do in a specific scenario. Everything described here reflects education, experience, and one structured understanding of how mortgages, liabilities, and private remedies can operate.
The Deed of Repentance framework is law‑structured and tailored specifically to mortgages and real property. Its purpose is to help clarify and, where possible, correct the liabilities attached to a home — liabilities that exist on an estimated 90–95% of properties, unless a truly private loan was created between two parties with a fully informed, transparent contract(two parties sign). For most homeowners, this is the legal and financial environment they occupy whether they realize it or not. This article is intended as a map that many wish they had been given years earlier by the professionals they not only trusted, but paid with real consideration/value.
For those who find this framework resonant, the next step is study and observation, not blind action. Re‑watch The Big Short with fresh eyes. Re‑examine existing mortgage documents. Learn the difference between the promissory note and the deed of trust/mortgage(security assignment). Explore materials on notices of liability and the work of Cal Washington and the InPowerMovement.
To go deeper into these foreclosure dynamics and private‑remedy strategies, consider following the ongoing series “Foreclosure Wars” on Spotify, Amazon, Apple, and other major podcast platforms — and be sure to watch the companion YouTube content for visual walk‑throughs of these concepts and processes. Like, share, and do the social work needed to get this information into the hands of other homeowners who may be quietly steamrolled by a system that depends on their confusion.
Above all, homeowners are encouraged to stand their ground, recognize that systemic silence and dishonor are the real problems, and remember: they are not merely “borrowers.” They are the lord of the Land — and it is time to begin acting accordingly.
Master the Strategies That Turn Fix-and-Flip Projects into Real Estate Wealth
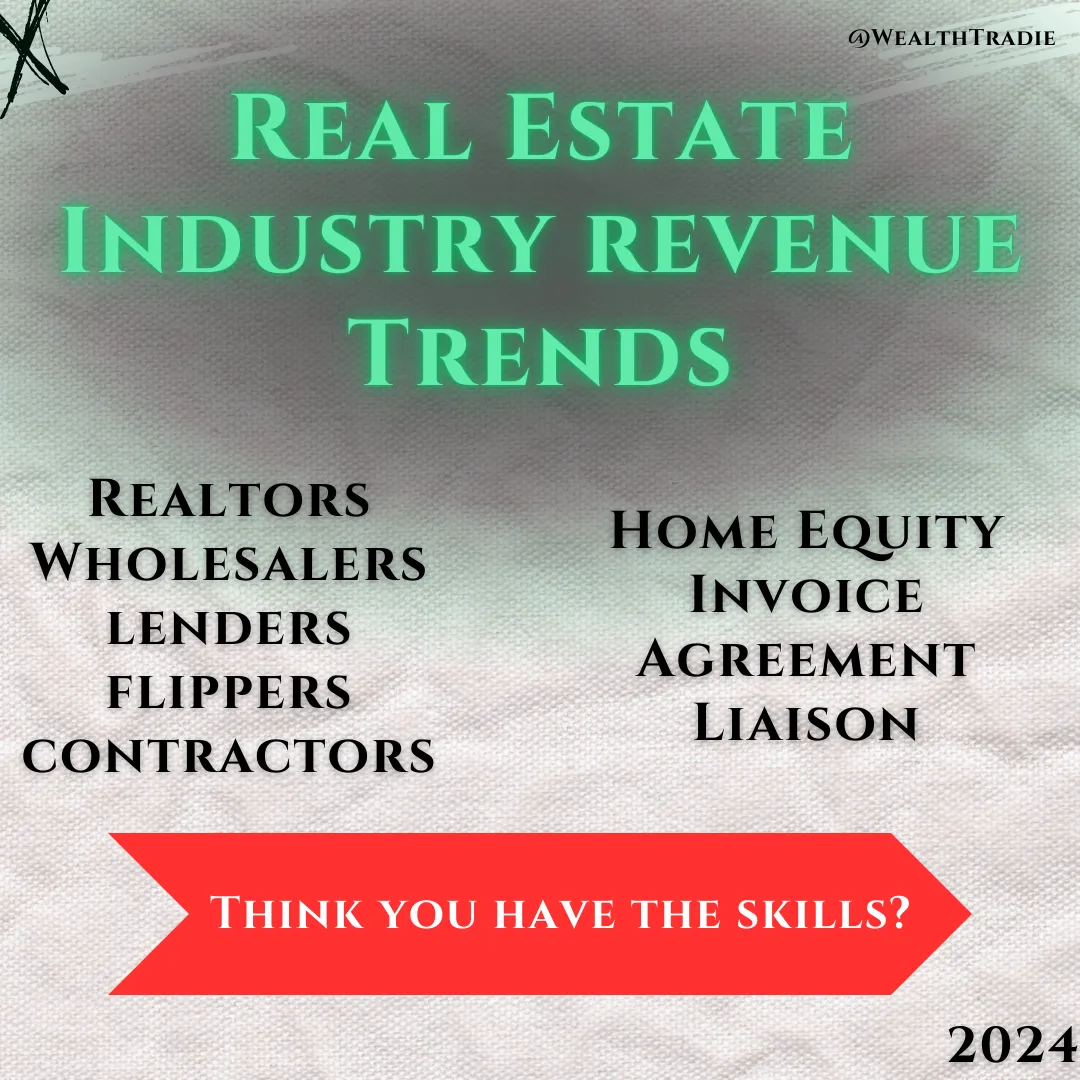
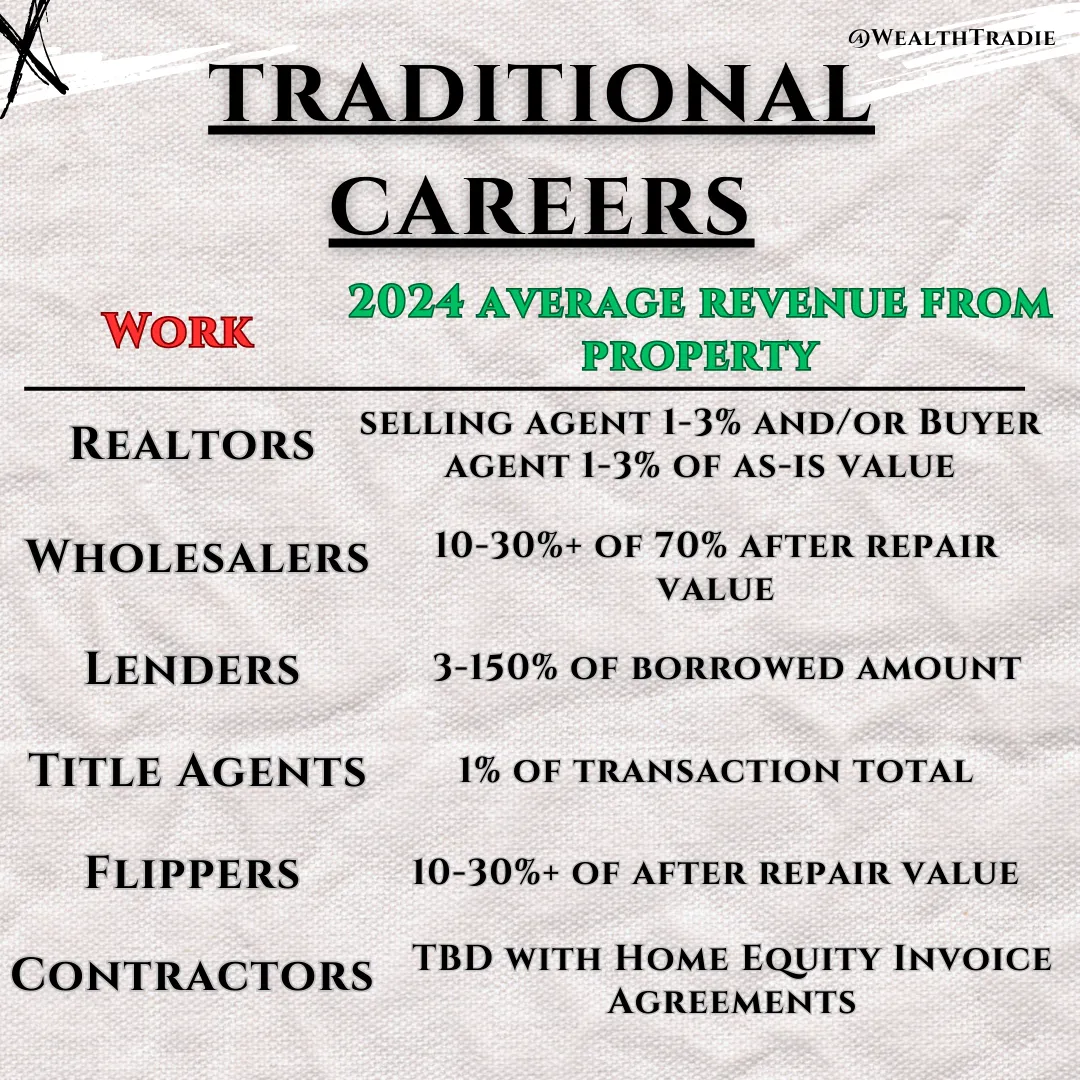
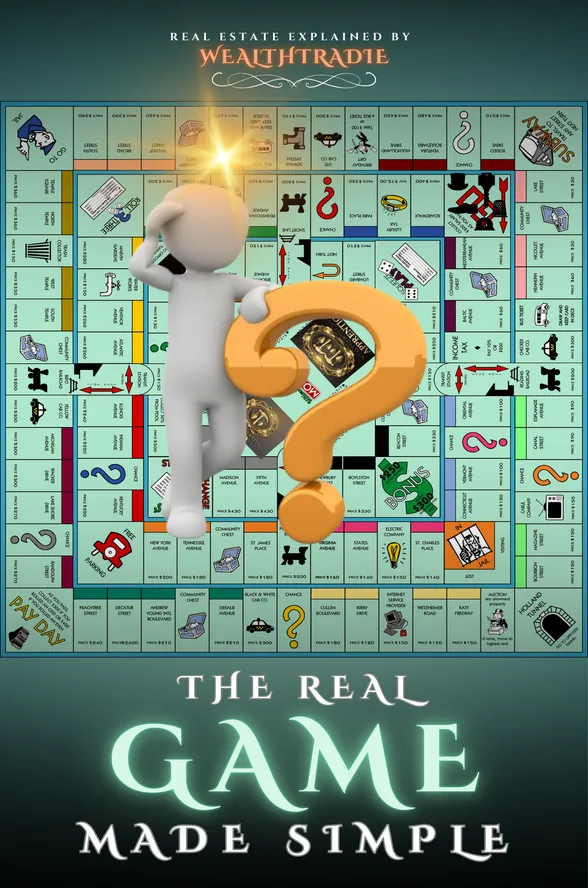
"The Real Game Made Simple"
–Your Beginning to Fix and Flip Wealth
it’s your ultimate guide to scaling and succeeding in the fix-and-flip business. Packed with actionable insights and strategies, it equips you with the tools to maximize profits, streamline projects, and make smarter decisions in a competitive market.
Why The Real Game Made Simple
is a must-read for fix-and-flippers:
✅ Maximize Your Returns:
Learn how to use Home Equity Invoice Agreements (HEIAs) to reduce upfront capital needs and boost profits on every flip.
✅ Streamline Your Process:
Uncover strategies to manage timelines, contractors, and budgets with precision.
✅ Build Long-Term Wealth:
Go beyond flipping—discover how to align your projects with equity-based strategies for lasting financial success.
STILL NOT SURE IF THIS IS FOR YOU?
POWER QUESTIONS
How does a Home Equity Invoice Agreement (HEIA) work?
HEIA allows Homeowners and HEIA Liaisons to finance renovations by leveraging a property’s equity instead of upfront cash or loans. Contractors are paid through a percentage of the property’s value after the work is completed, aligning their success with the property. This eliminates the need for traditional lenders and their fees, giving you more control and flexibility.
What if the contractor doesn’t deliver high-quality work?
With HEIA, contractors are held accountable because their payout is tied to the property’s value. The better the work, the higher the property’s value—and their earnings. This built-in motivation ensures quality work and on-time project completion within the time period specified, or loose out on entire equity on HEIA.
Is HEIA only for experienced fix-and-flippers?
Not at all! Whether you’re just starting or already scaling your business, HEIA provides a straightforward solution to fund and execute projects without relying on banks or lenders. Plus, our WealthTradie Apprenticeship bonus equips beginners with all the tools they need to succeed.
What if the property value doesn’t increase as expected?
HEIA accounts for market fluctuations through a risk reduction rate agreed upon upfront. This safeguards both Homeowner and the Contractor, ensuring a fair equity exchange based on realistic property and market conditions.
How do I know this is the right choice for me?
If you’re tired of lender delays, high costs, and limited scalability, HEIA is the perfect solution. It provides fast, flexible funding, ensures quality work, and reduces overall project costs, making it ideal for anyone in the fix-and-flip industry.
What kind of support do I get after becoming a HEIA Liaison?
You’ll have access to our Pro Membership training, priority support, and detailed resources that guide you through every step of using HEIA effectively. Plus, our community of WealthTradie professionals is always available to help with questions or challenges. WealthTradie push's their Homeowner leads directly to the nearest Liaison to the property. Providing you with free homeowner leads
Is there a guarantee?
Yes! We stand behind the value of HEIA and the WealthTradie system with a satisfaction guarantee. If you don’t see how HEIA can transform your business, let us know within 30 days for a full refund.
How can I make additional income with this program?
Through our 100% Revenue Share Affiliate Membership, you can earn uncapped income by referring others to HEIA and WealthTradie memberships. It’s a great way to generate extra revenue while helping others break free from traditional lending. This allows you to still scale using the previously most available scaling model in the real estate industry, Education.
Do I need a HEIA Liaison License to use a HEIA?
If you already are a Homeowner or Contractor, you do not need to have a HEIA Liaison License to use a HEIA. A Liaison is optional to use weather a contractor or homeowner need assistance in their real estate project.
Do I need a real estate license?
No, you don’t need a real estate license to be a HEIA Liaison. Unlike traditional real estate transactions, HEIA is structured as a joint venture agreement, not a real estate sales contract. As a Liaison, your role is to facilitate equity-based agreements between homeowners and contractors, aligning their interests for mutual benefit. This falls outside the scope of activities that require a real estate license, making it a unique and powerful tool for anyone looking to work in real estate without the licensing hurdles.
If you do, or have ever had a real estate license, we offer a 50% DISCOUNT ON A HEIA LIAISON LICENSE.
Can HEIA help me scale my flipping business?
Yes! With equity-based financing, you can take on more projects simultaneously, growing your portfolio and profits.
30 Day No-Questions Money Back Guarantee
TRY IT OUT RISK FREE
Get a 30 Day No-Questions Money Back Guarantee
That’s how confident we are that you’ll love your experience.
How it works
We’re confident you’ll love your experience, but if for any reason you don’t, you’re covered!
Try us out for 30 days, and if you’re not completely satisfied, simply reach out to us at [email protected], and we’ll refund your full investment—no questions asked. It’s that simple.
We want to ensure that you feel confident in making this decision, knowing you have nothing to lose and everything to gain.
30 Day No-Questions Money Back Guarantee


Copyright 2026 | WealthTradie™ | Privacy Policy | Terms & Conditions