WealthTradie.com
"Turning Hard Money into bullet proof money with proprietary contract structures"
The Master strategy for Lenders
The Power of Home Equity Invoice Agreements (HEIAs) for Lenders
Home Equity Invoice Agreements (HEIAs) are revolutionizing real estate lending by allowing lenders to directly invest in hard costs (materials and labor) rather than speculative property or quality values. This innovative financing model ensures higher security, direct asset-backed investments, and a scalable opportunity to fund more properties than ever before with deed and mechanical lien protection.
CLICK BELOW TO WATCH FIRST!
30 Day No-Questions Money Back Guarantee
endless construction need liquid capital and lenders now have a safe, secured, and wealthy way to fund real estate equity in the SIMPLEST way; through the construction of it
Why HEIAs Are the Future of Secured Real Estate Lending

🔹More Control– Invest in the real value creation process rather than fluctuating property prices with extra middlemen.
🔹Higher Security– A proprietary performance backed Deed, ensuring your investment is legally protected with double protection of mechanic liens regardless of deed position.
🔹More Deals, Less Risk– Fund multiple projects securely at once instead of locking capital into one high-risk property with less structure protection.
🔹Fast Liquidity– Get repaid faster than traditional real estate investments through higher structure and work quality, allowing for higher reinvestment cycles.
🔹Guaranteed ROI Potential– Partner with
contractors and homeowners who have a direct incentive to complete projects on time and at the highest value for everyone to share equitably.
INTRODUCING:
Home Equity Invoice Agreement Liaison License
Change the Game for Lenders
HERE’S HOW IT WORKS
Invest in Tangible Hard Costs
Traditional real estate lending relies on speculative values, exposing capital to market swings. HEIAs secure your investment with direct material and value accountability. protecting your downside while still tying you to the upside of market appreciation.
Secure Investments with Proprietary Deed
Unlike risky loans, HEIAs are secured by recorded equity on the deed. giving you priority repayment and an extra layer of security with direct material lien capabilities over deed positions in certain states
Unlock More Lending Opportunities
Traditional real estate requires large capital per deal. HEIAs let you scale by funding specific improvements across multiple properties, not full purchases with additional risks.
Take control of your real estate investments with a smarter, safer, and more scalable strategy. Become an HEIA Liaison today and start investing in secured, debt-free, equity-based real estate deals!
30 Day No-Questions Money Back Guarantee
Unlock the $36 Trillion Home Equity Market
The Future of Real Estate Financing
Before / Old Way
Speculative Value: Abstract market purchase values and costs that are subject to change
Relying on borrower: Relying on borrower credit and payments history for returns
limited to large, slow moving deals: Large purchase prices of property with slow moving acquisition processes
Market Fluctuations: Secured with borrower potential for default
Consistent management: Requires Mortgage payments, meaning borrower default can stall returns
After / New Way
Tangible hard costs: Real materials and labour that increases the homes actual value
backed by deed of trust: Dependant on property hard costs and its connected properties full value
fund multiple properties with the same amount: Invest in improvements rather then full purchases to speed up transactions
secured by added value: Secured by property's real improvements
Funds directly to contractor: Funds go directly to contractor with no management
30 Day No-Questions Money Back Guarantee
🔥 Exclusive 50% Discount for Licensed Loan Officers 🔥
Your Loan Officer License Just Became a Key to Unprecedented Wealth
—But Only for a Limited Time!
If you are a licensed Loan Officer, you’re already a trusted expert in your field. Now, WealthTradie invites you to elevate your career with the HEIA Liaison License, exclusively available at 50% off for a limited time.
This is your opportunity to:
✅Earn 100% revenue share by helping homeowners and contractors leverage Home Equity Invoice Agreements (HEIAs).
✅ Offer innovative equity-based financing solutions that deepen trust with buyers and sellers.
✅ Stand out in your market as a Loan Broker who provides next-level services.
Why is this offer exclusive?
We want to empower licensed Loan Officers like YOU to lead the charge in transforming the equity industry.
Introducing:
HEIA Master Liaison License
The #1 Scaling Method for Lenders
Here's Everything you get:
Step-by-Step Training Value: $5,611
A structured video series that walks you through each phase, ensuring you have everything you need to achieve using HEIA efficiently.
Personalized Implementation Plan Value: $250
A customized roadmap tailored to your specific goals, ensuring you take the right steps toward success with your real estate strategies.
Exclusive Q&A Sessions Value: $recurring
Get direct access to WealthTradie experts for ongoing support and clarity, helping you overcome challenges quickly.
Lifetime Wealth Multiplier Calculator Value: $270
Receive all future updates to the program, ensuring you stay ahead with the latest tools.
Done-for-You Contracts Value: $3,714
Save time and effort with ready-to-use documents that are designed for immediate implementation.
Normally: $an entire college degree
Today: A fraction of the costs
30 Day No-Questions Money Back Guarantee
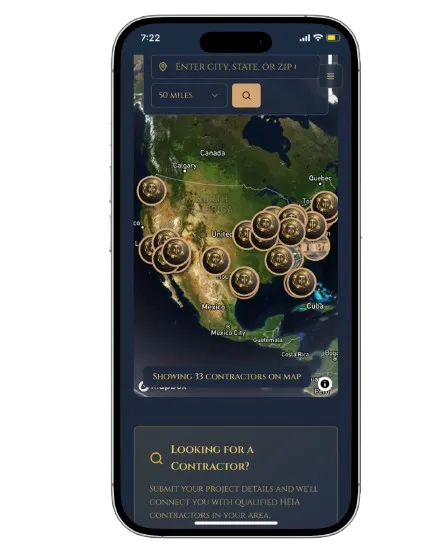
Connect with a contractor today!
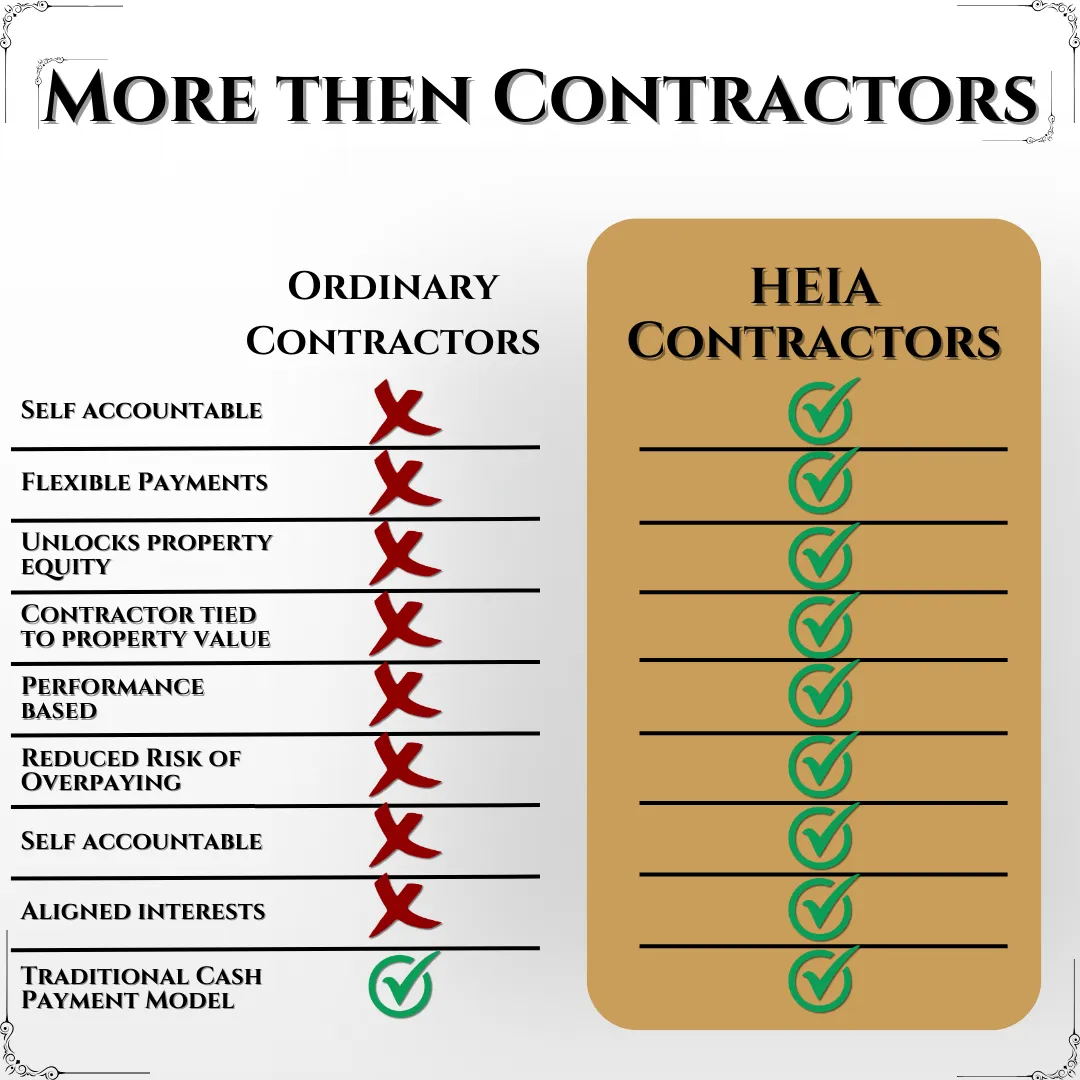
We wouldn't be at the tip of the spear leading this movement without understanding how hard it is to teach an old dog (investors) new tricks. don't believe our shiny red dress, connect with the boots on the ground and see for yourself with your current properties. WE guarantee that you will be able to see the difference and want your license on your next project.
PLUS, YOU ALSO GET
Amazing Bonuses When You Join Today
Bonus 1: WealthTradie Apprenticeship
Your All-in-One Toolbox for Scaling Success
The WealthTradie Apprentice Membership provides access to premium tools like equity exchange calculators, client generation resources, and advanced deal structuring contracts. Additionally, gain access to an exclusive support network of real estate professionals to help you troubleshoot and optimize your strategies.
Bonus 2: Pro Membership
Master the Art of Real Estate Success
The WealthTradie Pro Membership gives you step-by-step training to implement HEIA in your business. Learn how to attract homeowners, negotiate equity-based deals, and create win-win solutions for sellers and contractors alike. From beginner-friendly guidance to advanced deal strategies, this program equips you with everything you need to grow your business confidently.
Bonus 3: Full 100% Revenue Share Affiliate Membership
Earn While You Build Your Business
As a 100% revenue share affiliate, you can introduce HEIA and WealthTradie memberships to other real estate professionals while keeping 100% of the referral income. This provides an additional revenue stream that grows alongside your core real estate business.
These bonuses are designed to help you scale faster, work smarter, and earn more. With the WealthTradie Apprenticeship, Pro Membership, and Affiliate Program, you’ll have everything you need to dominate your market.
30 Day No-Questions Money Back Guarantee
Revolutionary
How others are utilizing HEIA
Peacefully Bear Arms: USPS, Witnesses & Bill of Lading
Homeownership, Private Law, USPS, Bill of Lading
How Homeowners Peacefully Bear Arms Using USPS, Witnesses, and a Bill of Lading
This article explains, in practical terms, how homeowners are using old‑school private law tools so they do not have to rely solely on a public court system they perceive as deeply compromised. It is based on education and experience shared in the Foreclosure Wars video series and similar teachings. The goal is to show homeowners how to stand in honor, create their own record, and avoid feeding an industry that thrives on controversy. It is educational information only, not legal advice.
Why Many Homeowners No Longer Trust the Public Court System
A growing number of homeowners do not rely on the public court system to protect their homes, families, or rights. In their experience, district attorneys, sheriffs, and even judges have been seen lying under oath or misrepresenting documents in ways that appear deliberate rather than accidental. One commonly cited example involves a judge pointing at a page, claiming to see the word “deed” on it, then handing the document back and no one in the room being able to find that word anywhere. For many observers, that is not a simple mistake; it is seen as fraud and industry protection, not justice.
For those seeking a visual sense of how deep this perceived rot goes, films like Just Mercy offer a sobering portrait. Viewers often describe it not as fiction, but as a mirror of systemic abuse. Similarly, The Big Short exposes how synthetic CDOs and paper games were engineered to keep ordinary people confused while insiders profited. In the foreclosure and mortgage world, homeowners see a parallel in the “mail room excuse”: “We never got your letter; an employee messed up.” These patterns are understood as part of a larger system designed to keep borrowers chasing ghosts while lenders and servicers keep the house, the equity, the time, and the peace of the homeowner.
📌 Key Takeaway: Many homeowners view the modern court system not as a neutral forum for justice, but as a mechanism for preserving financial and legal industries built on controversy.
For these reasons, some homeowners describe the public court system, as it stands in 2026, as corrupted. In their view, it is less about ethics and more about securing an industry. Rather than building their security on what they see as shifting institutional sand, they turn to private law tools that pre‑date the modern court system: Lex Mercatoria (the law of merchants), trust law, and postal jurisdiction. These are sometimes contrasted with what scholars at places like Harvard have started calling “retail law” – a rebranding of long‑standing private contract principles that have quietly existed alongside public courts for centuries.
“Peacefully Bearing Arms” as a Homeowner: What That Really Means
Within the Foreclosure Wars communities, the phrase “peacefully bear arms” does not refer to physical confrontation, shouting matches with sheriffs, or dramatic courtroom showdowns. Instead, it refers to using lawful, documented tools that allow a homeowner to defend property and position without stepping into the public court’s arena. The “arms” in this context are paperwork, witnesses, and postal records so complete that there is no controversy left for a public court to pretend it needs to resolve.
In practical terms, this approach for homeowners typically involves:
Two independent witnesses – real, disinterested adults who observe what goes into each envelope and how it is mailed.
The United States Postal Service (USPS) – a federal‑level postal jurisdiction with its own statutory framework, often compared to a bank’s position “next to” rather than “under” the federal government. Private carriers like UPS or FedEx are viewed as “baby jurisdictions” without the same evidentiary weight.
A Bill of Lading – a cargo manifest or receipt describing what is inside each envelope, tied to specific USPS certified mail tracking numbers, witnessed and signed, forming a third‑party trust record.
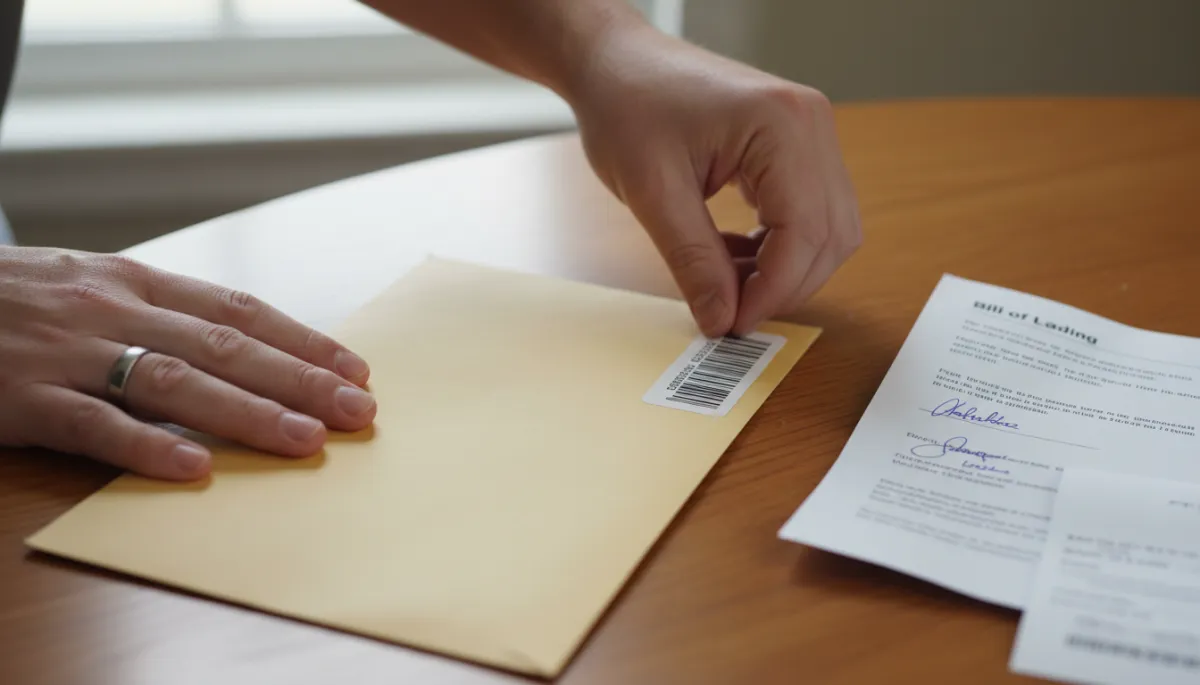
Tying each envelope to a Bill of Lading turns simple mail into structured, evidentiary record.
Why USPS Is Preferred Over Online Shortcuts and Private Carriers
Certified mail labels can be generated online, printed at home, and dropped off with little ceremony. While convenient, that process alone leaves a critical evidentiary gap. USPS certified tracking only proves that something was mailed from point A to point B. It does not prove what was actually placed inside the envelope. That gap is precisely where, according to many homeowners, shysters and fraudsters operate. They can claim, “We never got that notice,” or “What you say you sent is not what we received.”
💡 Pro Tip: Tracking numbers alone are rarely enough. The contents of the envelope must be tied to those numbers through witnesses and documentation.
To close that gap, practitioners of this method combine USPS certified mail with witnesses and a Bill of Lading. The USPS role is to provide a federal postal record: date, time, origin, and destination. The witnesses and Bill of Lading supply the missing piece – what was mailed. Together, they transform a simple mailing into a bona fide private record that can stand on its own, reducing the need for homeowners to appear in public court to “testify” about what they sent, unless serious fraud and forgery is done.
What a Bill of Lading Really Is (And Why Homeowners Use It)
The phrase “Bill of Lading” can sound intimidating, and some attorneys AT law may dismiss it as “just an invoice.” However, the term “bill” is much broader. Consider the Bill of Rights or the “bills” legislatures pass into law. A bill is fundamentally a formal written instrument. In commercial and shipping contexts, a Bill of Lading is a cargo manifest – a written record describing the goods being carried and who they are going to.
In the homeowner’s private law context, the “cargo” is not boxes on a ship but documents: notices, Bills of Exchange, affidavits, personal/private information, and other records. The Bill of Lading becomes the paper that states:
Who is sending which documents,
To which respondent or respondents,
Under which USPS certified mail tracking numbers,
Witnessed and signed by two independent third parties.
Functionally, this Bill of Lading operates as an affidavit of contents. Importantly, in the approach described in the Foreclosure Wars materials, it is not signed by the homeowner who benefits from the mailing. It is signed by third‑party witnesses. This design helps avoid accusations that the homeowner “made it up later” and instead establishes a third‑party trust. When multiple independent parties confirm the same record, there is far less room for a public court to claim there is a genuine controversy that requires its intervention.
Step‑by‑Step: Using a Bill of Lading With USPS and Witnesses
The following steps summarize how this process is typically described to homeowners. It is presented for clarity and education only; each person remains responsible for their own choices and research.
Gather the documents. These may include notices to a bank, servicer, county office, or any party involved with the property. In some approaches, this can also include a Bill of Exchange – treated as a form of United States Dollar payment instrument. The principle asserted is that if a party accepts United States Dollars, a properly executed Bill of Exchange constitutes lawful payment. If that party denies or refuses it, proponents argue that the obligation has still been discharged on the sender’s side; any failure to credit the account becomes the recipient’s issue, not the homeowner’s that now has a third party executed receipt of the transaction/correspondence.
Invite two independent witnesses. These should be adults who are not under the homeowner’s control and who can honestly attest, if ever needed, to what they saw. InPowerMovement materials highlight two‑witness statutes and “higher authority” structures found in various jurisdictions. The Bill of Lading process simply applies those principles to everyday homeowner mailings.
Prepare the Bill of Lading. A homeowner may use a template or craft a simple form. For each respondent, the Bill of Lading typically lists:
– The respondent’s name and mailing address,
– A short description of the documents being sent (for example, “Notice of Claim and Bill of Exchange”),
– A space to record the USPS certified mail tracking number sticker that was assigned to that envelope.Obtain certified mail stickers at the post office. Rather than using regular mail, practitioners of this method almost always use certified mail with electronic return receipt. Each certified mail sticker has a top portion (a narrow strip with the tracking number) and a larger label that adheres to the envelope itself.
Attach tracking numbers to the Bill of Lading. The homeowner peels off the top portion of each certified mail sticker and places it on the Bill of Lading next to the corresponding respondent’s entry. This step ties each recipient to a specific tracking number on a single document. That Bill of Lading then becomes an original record(bill) in the homeowner’s private files.
Pack the envelopes in front of both witnesses. With everyone present at the table, the homeowner:
– Shows the documents,
– Places the correct documents into each labeled envelope (to include copy of signed bill of lading),
The witnesses are not guessing; they are observing exactly which documents go into which envelopes.Apply the certified mail stickers to the envelopes. The larger portion of each sticker is then affixed to its envelope. Some practitioners intentionally place the label so that it wraps over an edge – partly on the front and partly on the back – making any attempt to remove or tamper with it more obvious. These small physical details can matter when dealing with institutions that may resist acknowledging a record.
Have both witnesses sign the Bill of Lading. Once the envelopes are sealed and labeled, the two witnesses sign and date the Bill of Lading, affirming that:
– They saw the documents,
– They watched those documents placed into the correct envelopes,
– They saw the envelopes sealed and labeled with those exact tracking numbers.Make copies for the recipients. The original Bill of Lading remains with the homeowner in private records. Copies are placed inside each envelope so that every respondent can see a description of what was sent and the associated tracking number. This anticipates the classic question, “What did you send?” by embedding the answer directly into the mailing itself.
Obtain a USPS hand‑applied round‑date stamp. At the USPS counter, some clerks may say that the machine‑printed bar code and date are sufficient. Practitioners of this method, however, specifically request the original individual post office's unique date stamp on both the certified receipts and, when possible, on the Bill of Lading(not common). That hand‑applied stamp makes it much harder for anyone to fabricate or alter the record later. If a later “copy” appears with a different stamp, the discrepancy is easier to detect.
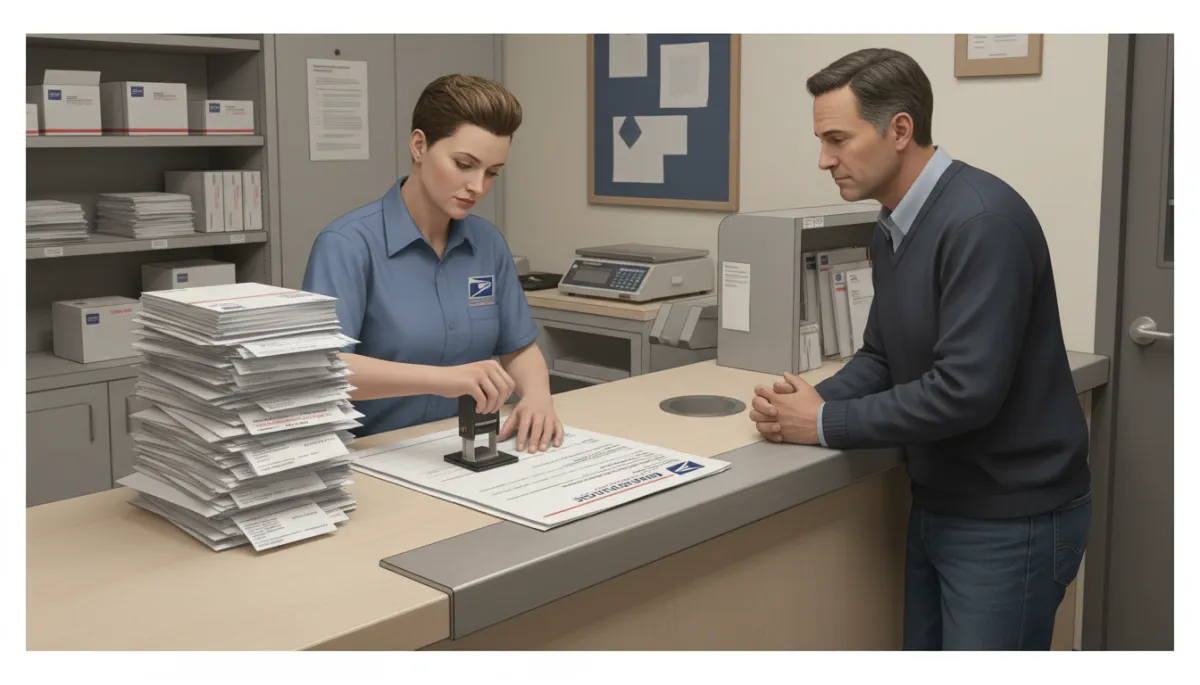
A live USPS round-date stamp helps distinguish the original record from later imitations or disputes.
Building Third‑Party Trust and Closing Common Excuses
After completing this process, a homeowner holds a layered evidentiary package:
Two independent witnesses confirming the contents and the mailing process,
USPS certified tracking showing that each envelope went to the correct address,
Electronic signature or delivery confirmation, supporting the maxim that “notice to agent is notice to principal; notice to principal is notice to agent”,
An original Bill of Lading tying all of these elements into one coherent private record.
“Who controls the record controls the narrative.”
When a bank, servicer, or attorney later claims, “We never received that,” the homeowner is no longer relying on memory or verbal argument(hersey). The witnesses, USPS tracking, electronic receipt, and Bill of Lading form a third‑party trust structure. If someone signed for the mail but claims not to have been an authorized agent, that party and their principal may be stepping into mail fraud territory, not the homeowner. The homeowner’s role is to act in honor, document thoroughly, and avoid unnecessary confrontation.
Old‑School Private Law: Lex Mercatoria, InPowerMovement, and Case Lessons
The approach described here is not a new invention. It draws on Lex Mercatoria, the historical “law of merchants” that governed private contracts and commerce long before modern nation‑states developed their court systems. Many of its concepts are reflected in definitions found in resources like Black’s Law Dictionary. Contemporary legal academics from Harvard are attempting to repackage aspects of this tradition as “retail law,” but the underlying principles are centuries old: private parties can structure their own contracts and records, and those records can carry significant weight.
Groups such as the InPowerMovement focus on surfacing statutes and case law that support these ideas, including two‑witness rules and hierarchies of authority. Their materials encourage homeowners to locate tools that have been “hiding in plain sight” within existing lawful frameworks. The Bill of Lading and USPS process is one way some homeowners apply those principles in daily life, keeping as much of their affairs as possible within private law rather than public court processes.
Historical examples reinforce this tension between centralized financial control and private contract rights. Andrew Jackson, for instance, vehemently opposed the type of central bank note system later associated with the Federal Reserve’s Notes. Many observers see the placement of his portrait on such notes as ironic, even insulting, given his resistance to centralized monetary power. That same tension surfaces today when homeowners explore Bills of Exchange and other private contract instruments to settle debts in a system that often pretends only one narrow form of “legal tender” is lawfully valid, so long as it keeps borrowers dependent.
Cases like Heinz v. North Carolina are sometimes studied in these circles not as magic bullets, but as illustrations of how jurisdiction, procedure, and record‑keeping can either empower or corner an individual in a process. The central lesson many draw is that the party who controls the record tends to control the narrative. By using a Bill of Lading, witnesses, USPS certified mail, and clear documentation, homeowners aim to create a record that “speaks for itself” long before any courtroom appearance(controversy) is even contemplated.
Educational Purpose and Important Disclaimer
Many homeowners are searching for ways to protect their homes without walking blindly into a system they experience as adversarial and profit‑driven. The methods described here – two witnesses, USPS certified mail, Bills of Lading, Bills of Exchange, and private contract principles rooted in Lex Mercatoria – are part of that exploration. They represent one educational perspective on how to reduce reliance on public courts and to build stronger private records.
⚠️ Warning: Misunderstanding or misapplying law or legal concepts can have serious consequences. Always research thoroughly and consult qualified professionals where appropriate/needed.
However, it is crucial to be clear about the nature of this information. This article is not written by an attorney and does not provide legal or lawful advice. It summarizes educational content and personal experiences shared in foreclosure‑focused communities such as Foreclosure Wars and the InPowerMovement. Every reader remains responsible for their own research, decisions, and outcomes. Those who wish to go deeper should study statutes, case law, Lex Mercatoria, and reputable educational materials, verifying every claim for themselves.
In summary, the Bill of Lading process, combined with USPS certified mail, two independent witnesses, and careful documentation, is presented by its proponents as a powerful way for homeowners to “peacefully bear arms” in the legal and commercial realm. It aims to bind facts in the tangible, three‑dimensional world in a way that also establishes trust and clarity in the abstract realm of records and rights. Used thoughtfully and in honor, it can help shrink controversy and reduce the need for public courts to “decide” a homeowner’s reality on loose or missing records.
Disclaimer: This entire article is for educational purposes only. It reflects concepts and experiences shared in private law and homeowner education communities. It does not constitute legal or lawful advice, does not create any attorney‑client relationship, and should not be relied upon as a substitute for professional counsel.
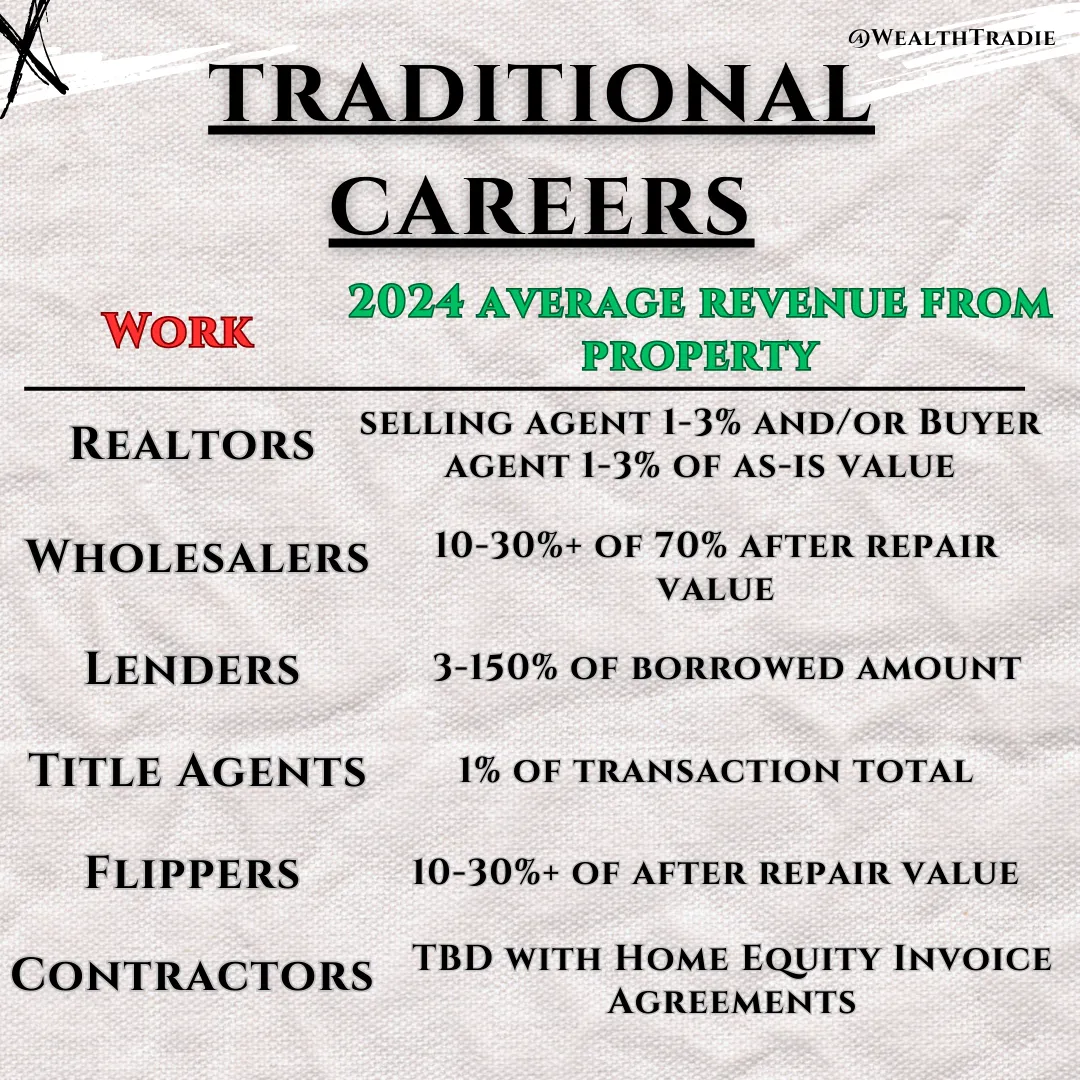
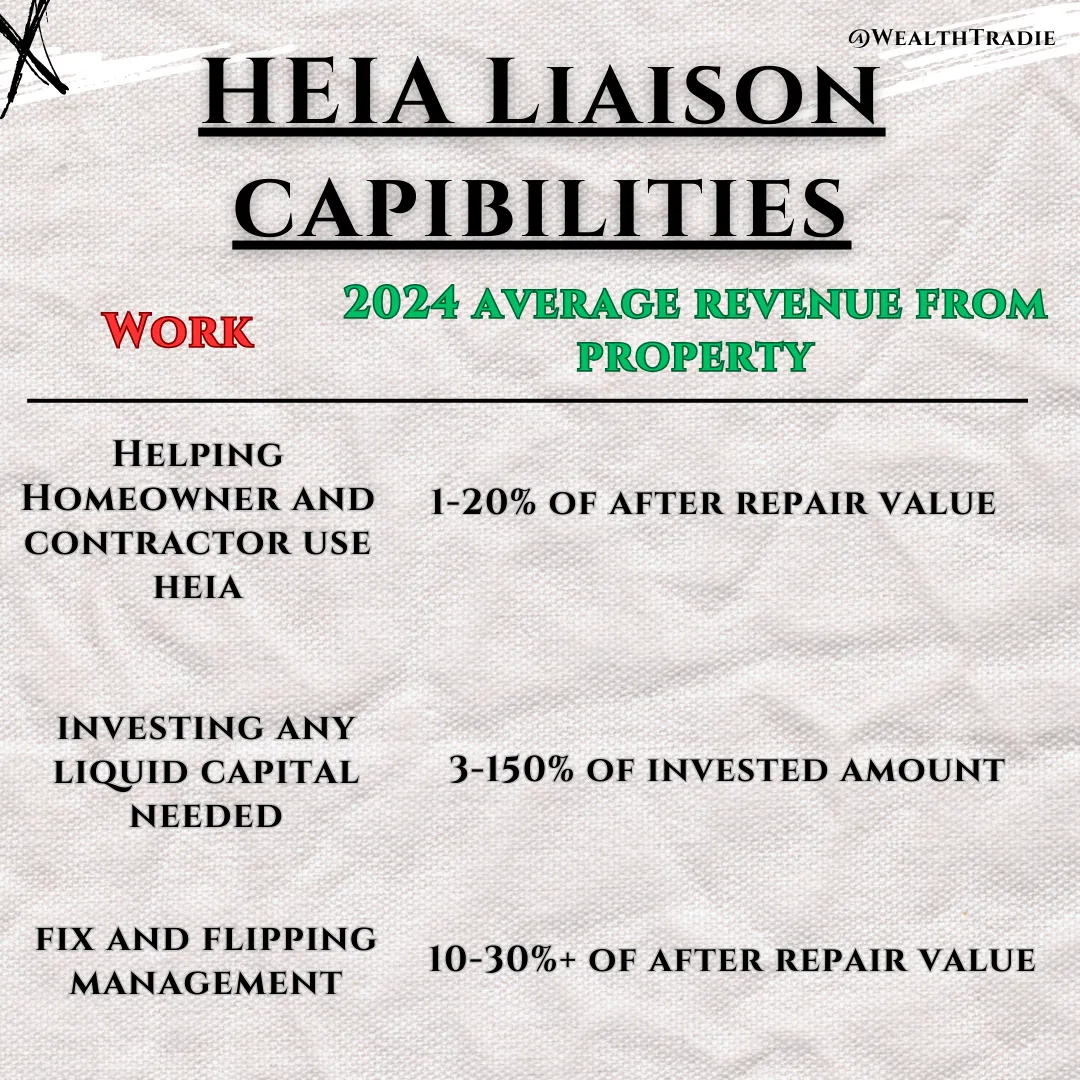
Best tools for real estate financing professionals
"The Real Game Made Simple"
–A Must-Read
is more than just a book – it’s your guide to unlocking success in the real estate industry. Packed with actionable insights and real-world strategies, it’s designed to help realtors navigate challenges, build wealth, and thrive in a competitive market.
Here’s why top real estate agents are calling it a
game-changer:
✅ Deepen Your Expertise:
Learn how to align with clients' needs, understand market dynamics, and position yourself as the go-to realtor in your area.
✅ Build Wealth Smarter:
Explore innovative equity-based strategies, like HEIAs, to elevate your client relationships and close deals that benefit everyone.
✅ Avoid Common Pitfalls:
Uncover hidden industry challenges and learn how to sidestep them with confidence.
TRY IT OUT RISK FREE
Get a 30 Day No-Questions Money Back Guarantee
That’s how confident we are that you’ll love your experience.
How it works
We’re confident you’ll love your experience, but if for any reason you don’t, you’re covered!
Try us out for 30 days, and if you’re not completely satisfied, simply reach out to us at [email protected], and we’ll refund your full investment—no questions asked. It’s that simple.
We want to ensure that you feel confident in making this decision, knowing you have nothing to lose and everything to gain.
30 Day No-Questions Money Back Guarantee
STILL NOT SURE IF THIS IS FOR YOU?
POWER QUESTIONS
What makes HEIA lending safer than traditional real estate loans?
HEIAs are secured by a Deed of Trust, ensuring lenders have a legal claim to the property’s equity. Unlike traditional loans or deeds that rely on borrower credit and fluctuating market values, HEIAs are backed by tangible home improvements—real, measurable assets that increase the property’s worth.
How does lending on HEIAs allow me to invest in more properties at once?
Instead of locking your capital into a single, large mortgage or home purchase, HEIAs allow you to fund the hard costs (materials, labor, renovations) of multiple properties simultaneously. This diversification spreads risk and accelerates return cycles.
What guarantees that my investment is protected?
HEIAs are legally structured with recorded Deeds of Trust, ensuring lenders are prioritized for repayment before any unsecured creditors. Your investment is secured by the property itself and not dependent on borrower credit scores or fluctuating appraisals. You are guaranteed your equity as soon as you sign, and as long as you perform and do not break your agreement. You receive your equity value when the home is sold or the end of the HEIA term set.
Who actually receives my funding in an HEIA deal?
Unlike traditional real estate loans that send money to homeowners or third parties, HEIA funding goes directly to self accountable contractors who are paid in the properties equity too—ensuring transparency, accountability, and proper use of funds.
What happens if a homeowner sells their home before the HEIA is paid off?
If the home is sold, lenders receive their payout first, before any profits go to the homeowner and contractor. Because HEIAs are tied directly to home equity, the transaction is settled automatically at closing, ensuring timely repayment.
Can I liquidate my investment faster than traditional real estate loans?
Yes! HEIA investments offer faster liquidity cycles because they are based on project completions, not long-term mortgages. Once the home is improved and sold, your capital can be quickly reinvested into new HEIA deals without traditional transaction and underwriting times.
How do HEIAs reduce the risk of foreclosure?
Since HEIAs don’t rely on traditional loan payments, there’s no risk of missed mortgage payments or defaults impacting your return. Your repayment is tied to property appreciation, home equity, and successful renovation completion. If the home goes to foreclosure, the hard costs (material and labour) of the HEIA project are protected and follow the homeowner and/or property if not satisfied.
Why is lending on home improvements better than lending on speculative home values?
Traditional real estate investments depend on market speculation—which fluctuates with interest rates and economic conditions. HEIAs focus on tangible improvements that directly increase property value, making them a more stable, predictable investment with direct equity compensation.
What kinds of returns can I expect from HEIA lending?
Returns vary based on property type and project scope, but HEIA lenders often achieve higher returns with shorter hold times compared to traditional real estate investing. Since funds are secured by home equity and tied to improvement value, ROI is predictable and scalable.
How do I get started as an HEIA lender?
Becoming an HEIA lender is simple. You can start funding secure, equity-backed real estate deals immediately by partnering with vetted HEIA contractors and homeowners in need of capital. Grab a HEIA Liaison license and start funding contractors today!
30 Day No-Questions Money Back Guarantee


Copyright 2026 | WealthTradie™ | Privacy Policy | Terms & Conditions